 reva
Reselling Without a Registered Business in Poland
What działalność nierejestrowana allows, where the limits are and what happens when you pass them.
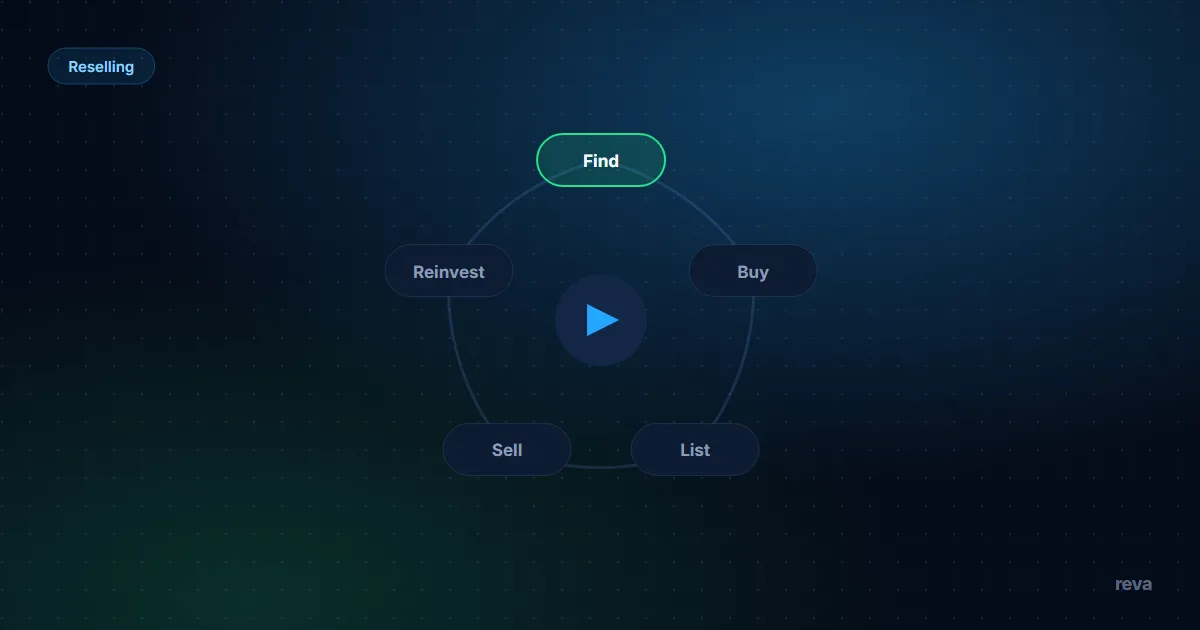
- Own belongings and bought stock follow different rules: a private item held over six months (from the end of the purchase month) and sold occasionally is not taxed; buying to resell points towards business activity.
- Unregistered activity (działalność nierejestrowana) lets you trade without CEIDG while revenue stays at or below 10,813.50 zł in every quarter of 2026 and you ran no business in the previous 60 months, with PIT-36 each year, a simplified sales record and no ZUS for selling goods.
- The limit counts revenue, not profit, across every marketplace you use. From the day you exceed it, biznes.gov.pl gives you 7 days to register in CEIDG.
- The VAT exemption does not cover online sales of goods such as cosmetics, electronics and household appliances, or sales of jewellery and car parts; biznes.gov.pl says those sellers register for VAT whatever their turnover, so check before buying such stock.
- Do I need a business to resell in Poland? Own items vs buying to resell
- The 6-month rule for private items
- Unregistered activity: the quarterly revenue limit
- What you must record and file (PIT-36, sales record)
- VAT exemption and why electronics and cosmetics are different
- What happens if you exceed the limit
- How DAC7 reporting fits in
- When to talk to an accountant
Do I need a business to resell in Poland? Not to sell your own belongings. Buying items to resell is different: it can run without registration as unregistered activity (działalność nierejestrowana), but only while your revenue stays at or below 10,813.50 zł in every quarter of 2026 and you ran no business in the previous 60 months. From the day you go over, biznes.gov.pl gives you 7 days to register in CEIDG.
Where an item came from decides the rules. Sources: biznes.gov.pl and podatki.gov.pl, read 13 September 2026. General information, not tax advice.
Do I need a business to resell in Poland? Own items vs buying to resell
- Your own belongings (a wardrobe clear-out, an unused console): tax depends on how long you owned them.
- Items bought to sell are different. biznes.gov.pl defines business activity as organised, continuous, profit-oriented activity in your own name, and buying to resell usually fits it. Where your own line falls is a question for an adviser.
- 1Bought to resell?If yes, skip to step 4: business sales are taxable however long you held the item.
- 2Own item held over 6 months?From the end of the purchase month. Occasional sale: not taxed, not reported.
- 3Own item sold within 6 monthsTaxable on PIT-36, even at a loss.
- 4Revenue at or below 10,813.50 zł every quarter?With no business in the previous 60 months, unregistered activity is available.
- 5Over the limitRegister in CEIDG within 7 days of exceeding it.
Account rules are separate: Vinted's catalogue rules (vinted.co.uk) bar individual users from listing items for commercial sale, and its Polish help page says Vinted Pro is not open to Polish businesses; see Vinted Pro in Poland. Private vs business seller covers how each marketplace defines a business seller.
The 6-month rule for private items
For a private (non-business) movable item, podatki.gov.pl counts six months from the end of the month of purchase. Sold within that half year, the sale is taxable even at a loss, and income is revenue minus the acquisition cost, plus outlays.
A short-hold sale goes on PIT-36, part E, row "art. 10 ust. 1 pkt 8 lit. d", filed between 15 February and 30 April. The tax scale on podatki.gov.pl is 12% up to 120,000 zł, less a 3,600 zł reduction, and above that 10,800 zł plus 32% of the excess.
Unregistered activity: the quarterly revenue limit
biznes.gov.pl caps unregistered activity at revenue of 225% of the minimum wage in any quarter. With the minimum wage at 4,806 zł from 1 January 2026, the cap is 10,813.50 zł per quarter. You can use the route only if:
- you ran no business activity in the previous 60 months (biznes.gov.pl counts a suspended business as not run);
- you are not caught by the restriction on foreigners since 1 June 2025 (see FAQ).
The cap counts revenue, not profit. biznes.gov.pl counts a sale when it is due, even before the buyer pays, and leaves out returned goods and discounts. Add up every platform: the limit applies to you, not to one account.
Decision rule: if your running total plus your listed items could pass 10,813.50 zł this quarter, talk to an adviser about registering first. The 7 days run from the moment you exceed the limit, not from when you notice. Whether buyer-paid shipping counts is not stated, so ask an adviser.
What you must record and file (PIT-36, sales record)
biznes.gov.pl lists these obligations:
- Keep a simplified sales record (uproszczona ewidencja sprzedaży), entering each day's sales before your first sale the next day
- File PIT-36 and pay the tax by 30 April, on the tax scale, with costs deducted; no monthly advances
- Keep proof of every purchase, because deductible costs must be documented
- Honour consumer rights, including the 14-day withdrawal right for distance sales
- No social or health insurance (ZUS) contributions for selling goods on this route
- Ask an adviser about the cash register (kasa fiskalna): the 20,000 zł threshold, and goods such as perfumes and telecom equipment that need one whatever the turnover
The reseller inventory and profit tracker shows how to add a quarter sheet that sums revenue against the limit.
VAT exemption and why electronics and cosmetics are different
biznes.gov.pl describes a subjective VAT exemption for sales up to 240,000 zł a year. It does not apply to online sales of goods such as cosmetic and toiletry products, computers and electronic products, and household appliances. The list also names jewellery and precious metals and car and motorcycle parts. Sell any of these and biznes.gov.pl says you register as an active VAT taxpayer whatever your sales.
For a reseller that plausibly means perfume, phones, consoles, laptops, rings and car parts, but legal categories are not marketplace categories, and the page doesn't say whether used goods differ from new. Decision rule: before buying such stock, ask a doradca podatkowy about VAT.
What happens if you exceed the limit
Once revenue passes the quarterly limit, biznes.gov.pl treats your activity as business activity and gives you 7 days to register in CEIDG. It adds that a new entrepreneur may be entitled to relief from social insurance contributions; ask an accountant whether it applies.
Set your own warning line. Example: acting at 80% of the cap means booking the accountant when the quarter reaches 8,650.80 zł.
What registration changes (ZUS, tax form, bookkeeping) is outside our sources, so most of the registered column is "Not stated".
| Own items, no business | Unregistered activity | Registered in CEIDG | |
|---|---|---|---|
| Entry in CEIDG | No | No | Yes |
| Quarterly revenue cap | Not applicable | Yes10,813.50 zł per quarter in 2026 | Not applicable |
| Income tax | Partlyonly if sold within 6 months | YesPIT-36, tax scale, costs deductible | Not statednot covered here |
| ZUS contributions | Not stated | Nofor sale of goods | Not statedask an accountant |
How DAC7 reporting fits in
DAC7 is a reporting rule for platforms, not a tax. The Ministry of Finance says a platform reports a seller of goods with at least 30 sales, or more than the equivalent of €2,000 paid, in a calendar year, and that a report doesn't automatically start an audit.
| DAC7 | Unregistered activity limit | |
|---|---|---|
| Who counts | Each platform, from its own records | You, across all channels |
| Period | Calendar year | Each quarter |
| Measure | 30 sales or more than €2,000 | 10,813.50 zł revenue |
You can stay under DAC7 on every platform and still pass the quarterly limit. DAC7 for resellers compares how Vinted, Allegro and OLX collect the data.
When to talk to an accountant
Ask a doradca podatkowy (tax adviser) or an accountant if:
- You mix your own items with stock bought to resell
- Your quarter is heading towards 10,813.50 zł
- You had a business, even a suspended one, in the previous 60 months
- You are a foreigner who is not an EU/EEA, Swiss or US citizen
- You plan to sell cosmetics, electronics, household appliances, jewellery or car parts
For marketplaces, shipping and scams, see reselling in Poland. For sourcing, pricing and scaling, start with how to start reselling in Europe.
Frequently asked questions
What is the unregistered activity limit in 2026?
Is selling my old clothes on Vinted taxed in Poland?
Do I pay ZUS on unregistered reselling?
Can a foreigner use unregistered activity?
Sources
- biznes.gov.pl: Działalność nierejestrowana (updated 05.05.2026) checked 13 Sept 2026
- podatki.gov.pl: Zbycie rzeczy ruchomej (updated 19.08.2026) checked 13 Sept 2026
- Ministerstwo Finansów (gov.pl): Co warto wiedzieć o dyrektywie DAC7 (25.04.2025) checked 13 Sept 2026
- Vinted Poland: Czym jest DAC7? checked 13 Sept 2026
- Vinted Poland help: commercial selling and Vinted Pro (4/1120) checked 13 Sept 2026
- Vinted UK: Catalogue rules checked 13 Sept 2026
Start with reva
One place to find underpriced items, check their market value and act before someone else does.
reva estimates prices from public listings. Estimates, not guarantees.Keep reading
How reselling works end to end in the EU and UK: sourcing, pricing, marketplaces, fees, taxes, shipping and scaling, with Poland examples in zł.
26 min read
How reselling works in Poland: Vinted, OLX and Allegro Lokalnie fees, shipping, lumpeks sourcing, DAC7 and the quarterly limit for unregistered sellers.
15 min read
What DAC7 means for resellers on Vinted, OLX and Allegro: the 30-sales or €2,000 trigger, what platforms collect, blocked payouts, and why it isn't a tax.
8 min read